
In BSC Holding, Inc. et al. v. Lexington Ins. Co., — Fed.Appx. –, 2014 WL 929194 (10th Cir., March 11, 2014), the Tenth Circuit recently underscored how difficult it can be for an insurer to demonstrate prejudice as a result of late notice. The District of Kansas had granted summary judgment to Lexington, but the Court of Appeals reversed and sent the matter back to the lower court, holding that “substantial prejudice” had not been shown despite the fact that the policyholder had waited two-and-one-half years to notify the carrier and had spent $2.5 million dollars before doing so.
Lyons Salt Company owned a salt mine in Kansas. In January 2008, mine workers detected an inflow of water into the mine, and the insured set out to determine the cause and to devise a solution. In April 2010, following an extensive investigation by geotechnical experts and engineers, the inflow was attributed to an improperly sealed oil well that was deforming overlying shale formations. The experts told Lyons that the situation was “dire” and that a quick remedy was required, and the insured immediately set about constructing a specially-designed concrete bulkhead to seal off part of the mine.
 Lyons notified Lexington of the water inflow in July 2010, after it had already spent $2.5 million on the problem. The insured sought coverage under six Lexington policies of “all risk” property insurance issued between March 2004 and April 2010. Suit was filed in the Spring of 2011 after Lexington refused to commit to reimbursement. The sworn statement in proof of loss that Lyons submitted in December of 2010 sought $7.5 million, and the policyholder was estimating that the total cost of investigating and fixing the intrusion would top $11 million as of last year.
In the trial court, Lexington argued that it had suffered prejudice, and the District of Kansas agreed, granting the insurer’s motion for summary judgment. On appeal, the Tenth Circuit assumed “that [Lyons] waited too long to notify Lexington,” but Judge Robert E. Bacharach nonetheless reversed, holding that Lexington had failed to show substantial prejudice.
Under Kansas law, an insurer can show prejudice by “presenting evidence that (1) its ability to investigate the claim has been lost; or (2) opportunities to negotiate settlement have been lost; or (3) opportunities to defend have been lost.” According to the Court of Appeals, “to demonstrate prejudice, the insurer must show that it would have handled some aspect of the investigation, discovery or defense differently, and that with this change, [the insurer] could have either defeated the underlying claims or settled the underlying claims for a lower sum than for what the insureds settled.” Read more ›


 Sandy struck several hours later, causing extensive flooding in lower Manhattan. The Bowling Green Network suffered “extensive water damage” from the flooding, and Con Edison spent the next several days pumping out the water and cleaning, testing, and – as necessary – replacing its equipment. The network was re-energized early in the morning on November 3.
 In January, the Senate passed a bill which called for a four-year delay of the rate increases imposed by the Biggert-Waters. House leaders, however, wanted a more permanent fix, and they also wanted to avoid adding to the insolvency of the NFIP. Thus, the Homeowner Flood Insurance Affordability Act was born. The bill proposes, among other things: (1) to roll back certain rate increase “triggers” so that policyholders will no longer face rate increases as a result of the sale of a home or a lapse in coverage; (2) to provide a refund for those who already got hit under the foregoing provisions; (3) to restore “grandfathering” so that homes and businesses that were previously built to code and later remapped into a higher risk area by FEMA won’t face rate increases due to the remapping; and (4) to impose a cap on FEMA’s ability to raise annual insurance premium rates. Under the bill, FEMA can still increase premiums for owners of homes built before the flood insurance rate maps, but the increases have a hard cap of 18 percent per year (down from 20 percent under Biggert-Waters), and will typically range from only 5 percent to 15 percent.
 The policyholder, Millennium Inorganic Chemicals, Ltd., processed titanium dioxide at its facility in Western Australia, using natural gas that it received via a pipeline. It purchased the gas from Alinta Sales Pty Ltd., a retail gas supplier. Alinta, in turn, purchased the gas it supplied to Millennium from others, including Apache Corporation.
 Faced with what she described as “an onslaught” of lawsuits, the district’s Chief Judge Carol Bagley Amon ordered the clerk to open a miscellaneous civil case captioned “In Re: Hurricane Sandy Cases,” Docket No. 14 MC 41, on January 10 “for the purposes of Pretrial Case Administration in all actions seeking insurance coverage for damage caused by Hurricane Sandy.” She simultaneously directed three magistrate judges “to evaluate and make a recommendation regarding how to best handle all Hurricane Sandy cases.”
 Peerless Insurance Company issued a $1 million fire insurance policy to Executive Plaza. This gave Executive the choice to select payment of “actual cash value” or payment of “replacement cost.” The policy also provided that Peerless would not pay the replacement cost for any loss or damage until the property had actually been repaired or replaced. Finally, the policy contained a suit limitation clause that required the insured to commence any legal action within two years from the date of loss.
 In October of 2005, Hurricane Wilma damaged three apartment complexes in Broward County, Florida. The property manager for all three was Banta Properties, Inc., a company owned by various Banta family members. The individual family members also owned two of the three properties at the time of the storm, having sold the third one (Parkcrest Apartments) to an unrelated, non-party entity two months beforehand.
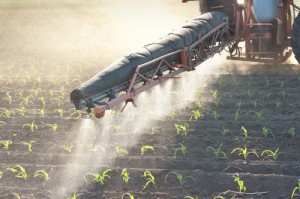 The Preislers owned a dairy farm with cattle, and they used a well to stock a pool on the property. For several years, they had defendant Kuettel’s Septic spray several thousand gallons of septage on their farmland. Kuettel’s Septic was in the business of removing, hauling, storing and disposing of the substance, which comes from septic tanks, grease traps, floor pits, and car washes. It is disposed of by either taking it to a treatment facility or by spreading it on farmland as a fertilizer. It contains high levels of nitrogen.
 Of course, when we’re dealing with commercial construction and property insurance, the most significant incentive for “going green” is probably economic. Over time, green buildings can reduce operating costs, improve employee productivity and satisfaction (a happy employee is a productive employee!), enhance asset value and profits, generate a better return on the owner’s investment (e.g., higher rents, sales prices and occupancy rates), reduce liability risks, and optimize the performance of a building during its life-cycle. There are also federal, state or local tax incentives for certain types of green construction.