
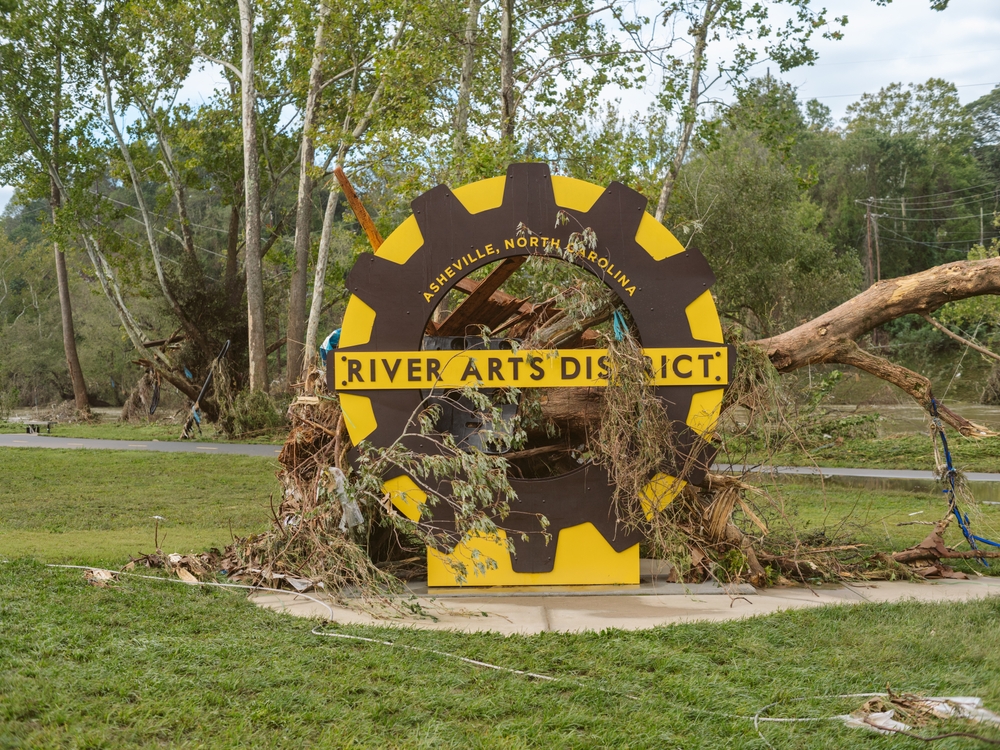
Business interruption losses after a catastrophic event often implicate overlapping causes, and a recent North Carolina decision demonstrates that even a broad conception of direct physical loss does not displace clear exclusionary language in a commercial property policy. In East Fork Pottery, LLC v. The Phoenix Insurance Company, 2026 WL 3409050 (W.D.N.C. Nov. 10, 2026), the Western District of North Carolina held that the Utility Services exclusion, reinforced by anti-concurrent causation language, barred coverage for Business Income losses following Hurricane Helene where an off-premises utility failure contributed to East Fork’s suspension of operations. The court also rejected East Fork’s unfair and deceptive trade practices claim, despite acknowledging that Phoenix’s denial letters were “not the model of clarity.” Together, these holdings…